
WASHINGTON, DC -The International Monetary Fund (IMF) says Guyana’s economy continues to expand at one of the highest rates in the world, supported by strong oil production and robust, broad-based non-oil activity.
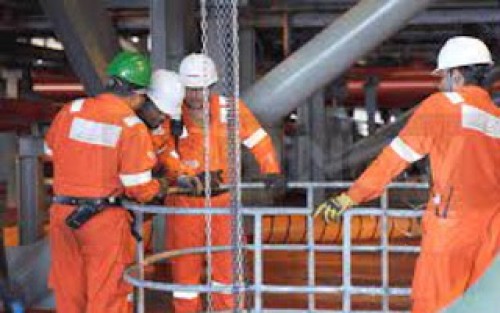 Oil workers in Guyana (File Photo)The IMF executive board which has just completed the Article IV Consultation with the country, said that real gross domestic product (GDP) grew by over 19 per cent last yea, with oil and non-oil GDP increasing by 21 per cent and 14 per cent, respectively.
It noted that oil production exceeded 900,000 barrels per day, labour market conditions strengthened further, and private credit supported economic activity.
“These trends broadly continued in the first half of 2026. Average inflation remained contained at 3.3 per cent in 2025 but edged up in 2026, reflecting higher global energy and food prices,” the Washington-based financial institution said, noting that the external position strengthened further, with the current account surplus widening, gross international reserves reaching about US1.4billion,andtheNaturalResourceFund(NRF)accumulatingaboutUS3.3 billion by end-2025.
The IMF said that strong oil revenues helped narrow the overall fiscal deficit to 5.5 per cent of GDP in 2025 while large public investments continued. The non-oil primary deficit as a share of non-oil GDP also declined slightly.
It said that the accumulation of oil revenue in the NRF has helped build external and fiscal buffers, and investments in physical and human capital have supported non-oil growth and social outcomes.
Monetary operations have helped contain liquidity and exchange rate pressures, while fiscal and supply-side measures have cushioned near-term price pressures. Economic fundamentals remain strong, while wage and competitiveness indicators warrant continued monitoring, the IMF executive board noted.
It said prudent macroeconomic policies continue to support Guyana’s strong growth. The authorities’ development strategy appropriately emphasizes diversification, resilience, and sustainability, while building buffers through continued rapid NRF accumulation and maintaining one of the lowest debt-to-GDP ratios in the Western Hemisphere.
Large public investments in physical and human capital are supporting non-oil growth and social outcomes. Monetary operations have helped contain liquidity and exchange rate pressures, while fiscal and supply-side measures have cushioned near-term price pressures. The IMF said that against this background, available indicators do not point to clear overheating or competitiveness pressures, though strong wage growth and wage-based real exchange rate measures warrant close monitoring.
The IMF said that the outlook remains highly favourable amid broadly balanced risks. Oil production is expected to continue expanding, and non-oil growth is projected to average about seven per cent over the medium term.
The external and fiscal positions should strengthen as new oil fields come onstream. Amid elevated global uncertainty, upside risks stem from further oil discoveries, stronger construction, and higher oil prices, while downside risks include oil price volatility, overheating pressures, and climate shocks.
The IMF said the fiscal deficit is expected to widen somewhat in 2026 due to transfers and electricity subsidies before improving in 2027.
It said if oil prices remain persistently high, a larger share of additional revenue should be saved in line with absorptive capacity.
“Spending should continue to prioritize productivity-enhancing projects and support for the vulnerable, while strengthening spending oversight and the performance of some key public enterprises. Consideration should be given to improving the targeting of subsidies, and broad price-mitigating measures should be gradually replaced with targeted support.”
Building on the authorities’ strong commitment to fiscal responsibility, a comprehensive medium- and long-term fiscal strategy would help preserve fiscal sustainability and intergenerational equity. Existing budget frameworks provide a strong basis for further developing medium- and long-term fiscal guideposts.
The IMF said that the non-oil primary balance could serve as the main operational target, strengthening gradually over the next decade to a level consistent with a chosen long-run anchor, such as preserving the real per capita value of NRF assets.
During the transition, public spending should remain aligned with development needs and absorptive capacity, accounting also for the high cost of public service delivery in a low population density country such as Guyana.
The IMF said monetary policy should remain consistent with the stabilized exchange rate arrangement and price stability. Liquidity should be managed through foreign exchange operations, as needed, and greater use of treasury bills and reserve requirements, to keep broad money growth broadly aligned with nominal non-oil GDP growth.
“Additional tightening would be warranted if demand, credit, or exchange rate pressures intensify. Over time, strengthening the monetary framework by activating the interest rate channel, deepening financial markets, improving macroprudential tools, and gradually reducing broad price-mitigating measures would enhance transmission.
“The current exchange rate regime remains appropriate, while greater flexibility could be considered over the medium term to facilitate macroeconomic adjustment and enhance resilience to shocks,” the IMF said.