
BANGKOK, Thailand – Belize Prime Minister John Briceño says dependence on imported energy leaves households, businesses, and public finances exposed to external shocks.
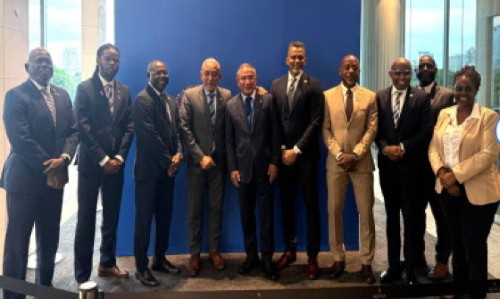 Addressing the Caribbean Ministerial Meeting, held on the margins of the 2026 Annual Meetings of the World Bank Group and the International Monetary Fund (IMF), Briceño highlighted the impact of rising energy costs on his country’s economy, noting that fuel prices had increased by 27.7 per cent since the crisis in the Strait of Hormuz.
The meeting here provided an opportunity to address the economic pressures facing Caribbean countries and the support needed to strengthen their resilience.
Prime Minister Briceño said that his government had sought to cushion the impact of rising costs through fuel tax reductions, while maintaining fiscal discipline.
But he said despite these pressures, Belize expects to maintain a primary surplus in 2026, while public debt continued its downward trend, reaching 66.4 per cent of gross domestic product (GDP) in August.
“Our immediate challenge has been to provide relief without compromising the fiscal position needed to withstand future shocks,” Prime Minister Briceño said, addressing also the longer-term challenges to Belize’s economic growth, including an ageing population, declining fertility, informal employment, and low female labour-force participation.
He spoke of the need to improve productivity, expand opportunities for young people and women, strengthen domestic revenue, and invest in skills, health, and resilient infrastructure.
Prime Minister Briceño called for closer regional cooperation in reducing costs and expanding opportunities for small states, particularly in renewable energy, green finance, payments, and technical capacity.
He urged the IMF, the World Bank, and other partners to provide targeted technical assistance and financing that responds to the particular needs and vulnerabilities of small states.
“We ask the Fund, the World Bank and our other development partners to support these efforts through relevant, targeted technical assistance, coupled with financing that is affordable, predictable and responsive to the particular needs and vulnerabilities of small states.”
Prime Minister Briceño also called for greater access to financing instruments that can provide timely support when countries face economic or disaster-related shocks, including contingent credit lines, catastrophe bonds, and parametric insurance.